Japan · GDP
+1.4%
Q2 growth, annualized — revised up from 1.1% on stronger capex
Wages are finally compounding in Tokyo. Chips are rewriting Seoul’s trade ledger. Moscow’s factories hum past expectations. The Gulf has unhooked growth from oil — and Singapore is once again the world’s most competitive address. Five economies. One new axis of capital.
The signals that define this quarter across the Asia–Gulf corridor — from a rate-hiking Tokyo to a chip-booming Seoul and a diversifying Gulf.
Tap a flag to open its September dossier — the numbers, the story and what the smart money is watching.
 Tokyo
The wage-price flywheel
Revised Cabinet Office data put Q2 GDP at 1.4% annualized, up from 1.1%, carried by a 1.6% jump in plant and equipment investment. Beneath it sits something bigger: six straight months of wage growth above 3%, and real paychecks that finally outrun inflation.
Markets have noticed. The yen touched a six-month high as the BOJ signaled a 25-basis-point hike on September 17–18 — with a terminal rate of 1.75% pencilled in by mid-2027.
 Seoul
The chip superclass
Driven by Samsung and SK Hynix HBM orders, August semiconductor shipments exploded to $46.65 billion — and the first ten days of September were even hotter: exports up 83%, chips up 270%. The cumulative 2026 trade surplus has reached $212.9 billion.
Unemployment sits at a 2% record low, and the state is answering the boom with a >$500 billion AI-chip “Southwest Mega Cluster” co-funded by the chaebol.
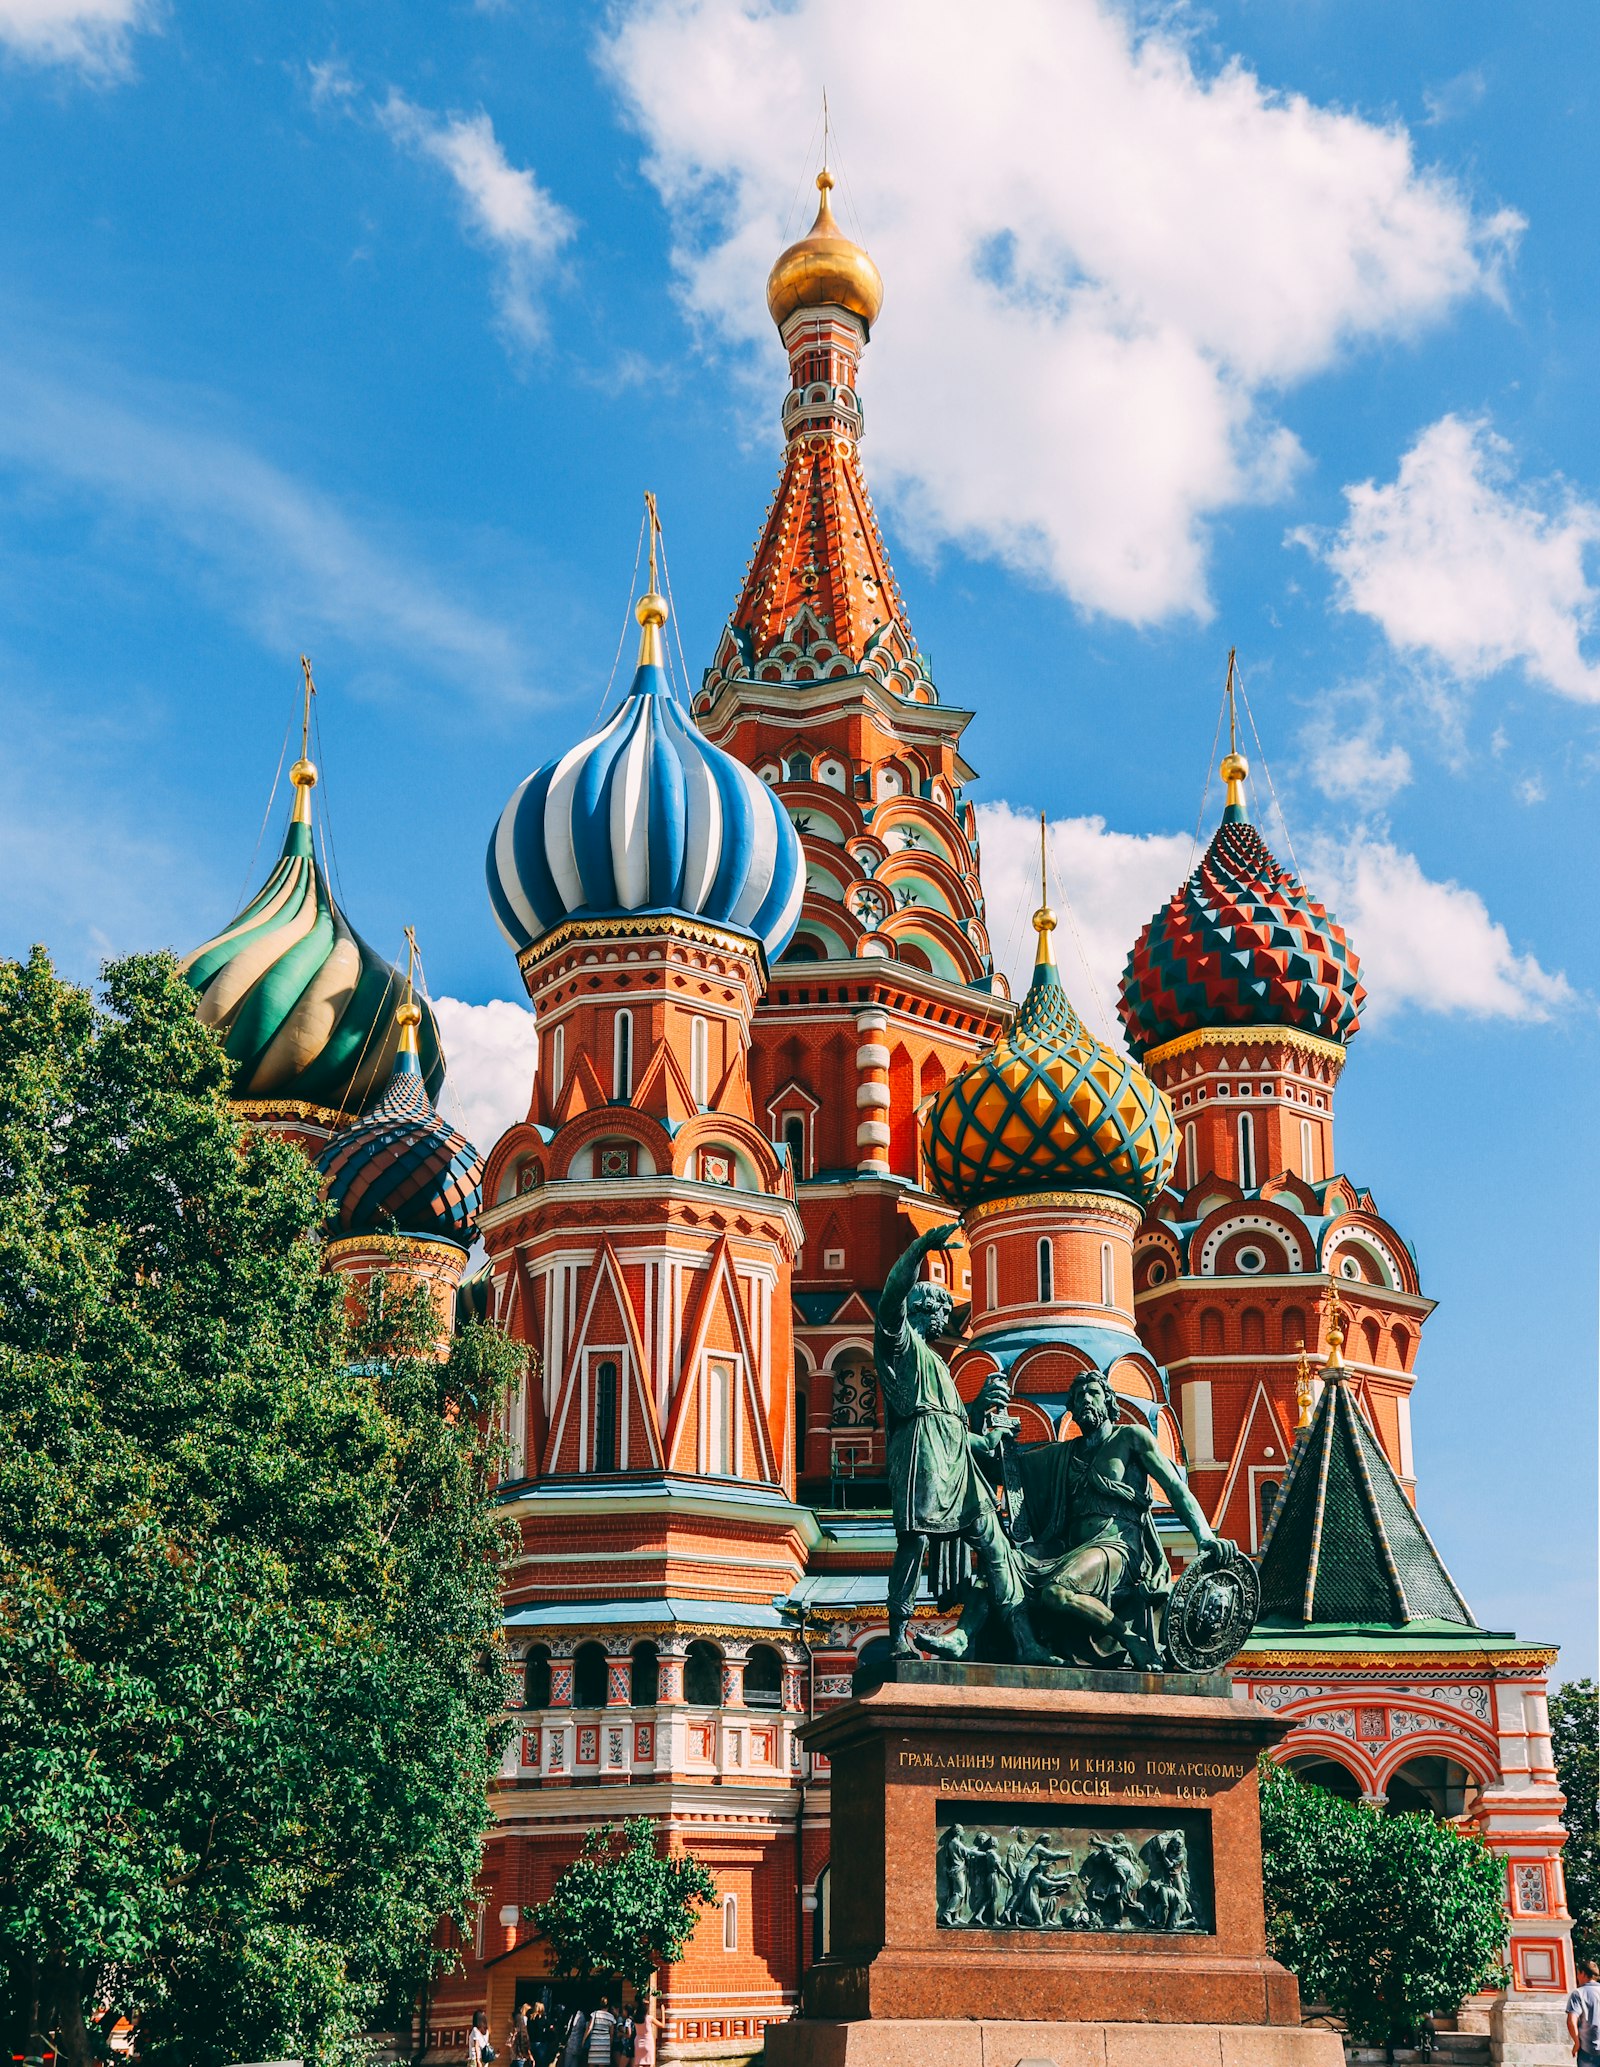 Moscow
The resistance economy
The feared contraction never arrived. The Economy Ministry revised first-half growth upward after a positive Q2, as heavy-machinery and industrial investment kept order books full and the ruble under less pressure.
With supply chains re-anchored toward Asia and the Middle East, domestic demand — from retail to industrial wages — is showing counter-cyclical resilience, while elevated oil prices have returned fiscal headroom.
 Dubai · Abu Dhabi
Post-oil, by design
Non-oil activity now drives 79.4% of GDP. DP World moved roughly 90 million TEU — overtaking Hong Kong — while finance, construction (+8.1%) and healthcare (+7.7%) all accelerate at once under the D33 agenda.
The world is voting with capital: a record $48.3 billion in FDI, the No. 2 greenfield destination globally, and nearly 40% of Middle East’s AI, clean-energy and climate-tech funding landing here.
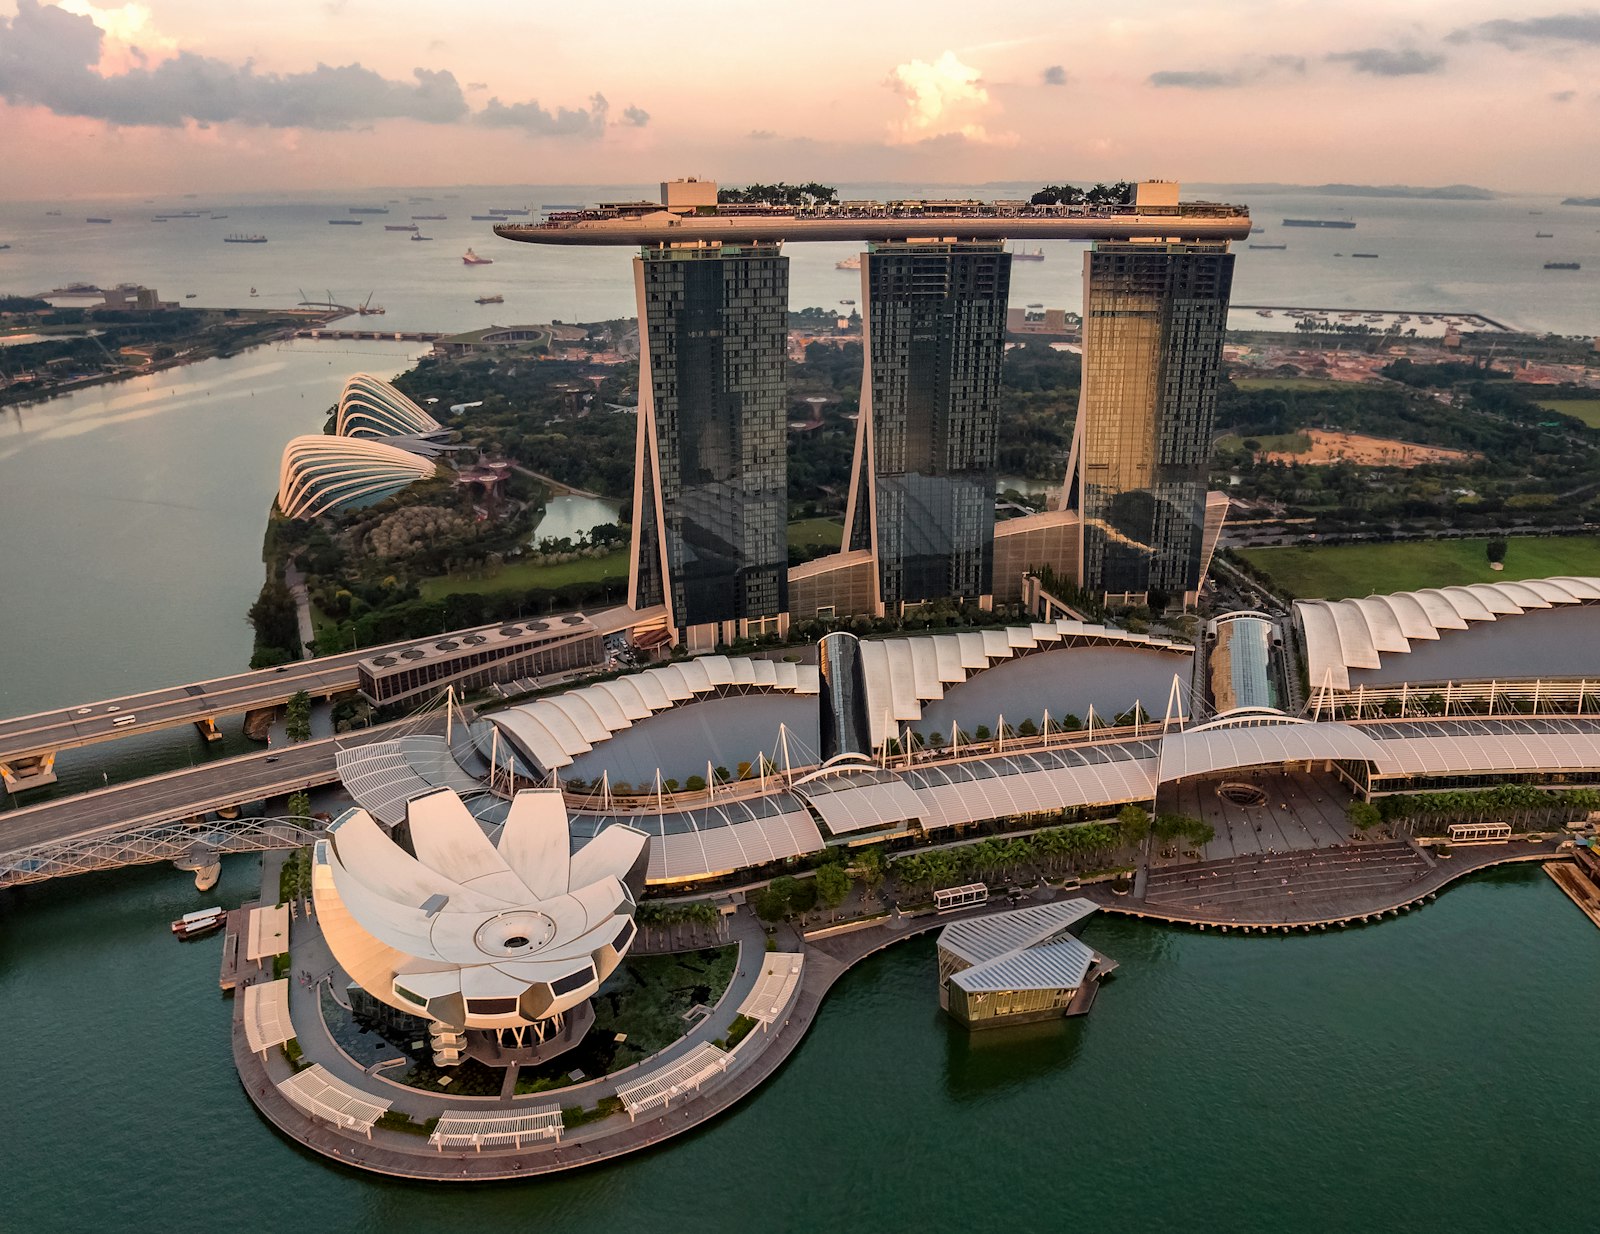 Singapore
The compounding harbour
The MTI lifted its full-year forecast to 4.5–5.5% as AI hardware demand supercharges non-oil domestic exports. UMC is pouring billions into fab capacity; Applied Materials just doubled cleanroom space at its $500M Tampines campus.
Meanwhile the budget added an S$800M semiconductor fund for advanced packaging and AI-chip R&D — and family-office wealth inflows pushed bank non-interest income to record highs while the S$NEER steepens.
Five deep reads on the forces repricing half the planet — reported from the numbers up.
 01 · JAPAN
For three decades Japan searched for an exit from deflation. In the summer of 2026, it may have found it — printed on a payroll.
July’s nominal wages rose 4.7% year-on-year, the fastest since 1997, and the sixth consecutive month above 3%. Strip out inflation and real pay still grew 2.4% — the strongest reading in nearly thirty years. Economists are calling it the confirmation of the “wage–price virtuous cycle” that two generations of policymakers only sketched on whiteboards.
Corporates are doing their part. The Q2 revision lifted business capex to +1.6%, as firms pour money into software and automation to offset chronic labor scarcity. Big manufacturers’ confidence sits at decidedly optimistic levels, with capital investment plans for the fiscal year up around 11%.
The BOJ is now the pivot. With August wholesale inflation running hot at 7.6%, the September 17–18 meeting is expected to deliver a 25bp hike to 1.25% — and a glide path toward a 1.75% terminal rate by Q2 2027. The yen has already climbed to a six-month high on the expectation.
 02 · SOUTH KOREA
No country in history had crossed the $100 billion monthly export line — until Korea did it in August, with chips doing the pushing.
August exports hit $102.25 billion, making Korea only the fourth nation ever to clear that bar in a single month. The engine: semiconductors up 209% to a record $46.65 billion, as Samsung and SK Hynix HBM output sold out through 2027.
September says it wasn’t a fluke. In the first ten days alone, exports surged 83% to $35 billion — chips up 270% at $16.5 billion — pushing the year’s cumulative trade surplus to a colossal $212.9 billion. The Korea Development Institute now sees 2026 growth at 3.2%, well above the IMF’s earlier call, on unemployment pinned at 2%.
Seoul is answering with concrete. The government-chaebol “AI Chip Southwest Mega Cluster” commits over $500 billion: Samsung’s ₩1,000 trillion (≈$646 billion) decade plan includes two new leading-edge foundries and a ₩360 trillion Yongin expansion; SK Hynix adds two HBM/memory fabs — and is even weighing a first-ever Japanese plant in Miyagi. Defense adds a second engine: a fresh $477 million rocket-launcher deal on NATO’s eastern flank.
 03 · RUSSIA
The recession call that never came true — and the industrial machine keeping it that way.
The Economy Ministry has revised first-half GDP growth up to +0.6% after a positive second quarter, formally burying the widespread forecasts of a deep contraction. Order books in high-precision equipment and heavy industry remain full.
The deeper story is a three-year, +18.3% manufacturing expansion financed by massive investment in heavy machinery — a build-out that has eased pressure on the ruble and balanced trade income. With supply chains re-routed toward Asia and the Middle East, both capital spending and private consumption have proven sturdier than expected.
Domestic signals back it up: unemployment sits near record lows, and catch-up wage growth is rippling from factories into retail. Meanwhile elevated oil prices have pushed fiscal revenue ahead of plan — restoring a buffer just as the industrial cycle matures.
 04 · UAE & DUBAI
The Gulf’s most audacious bet — that an oil economy could make itself irrelevant to oil — is officially paying off.
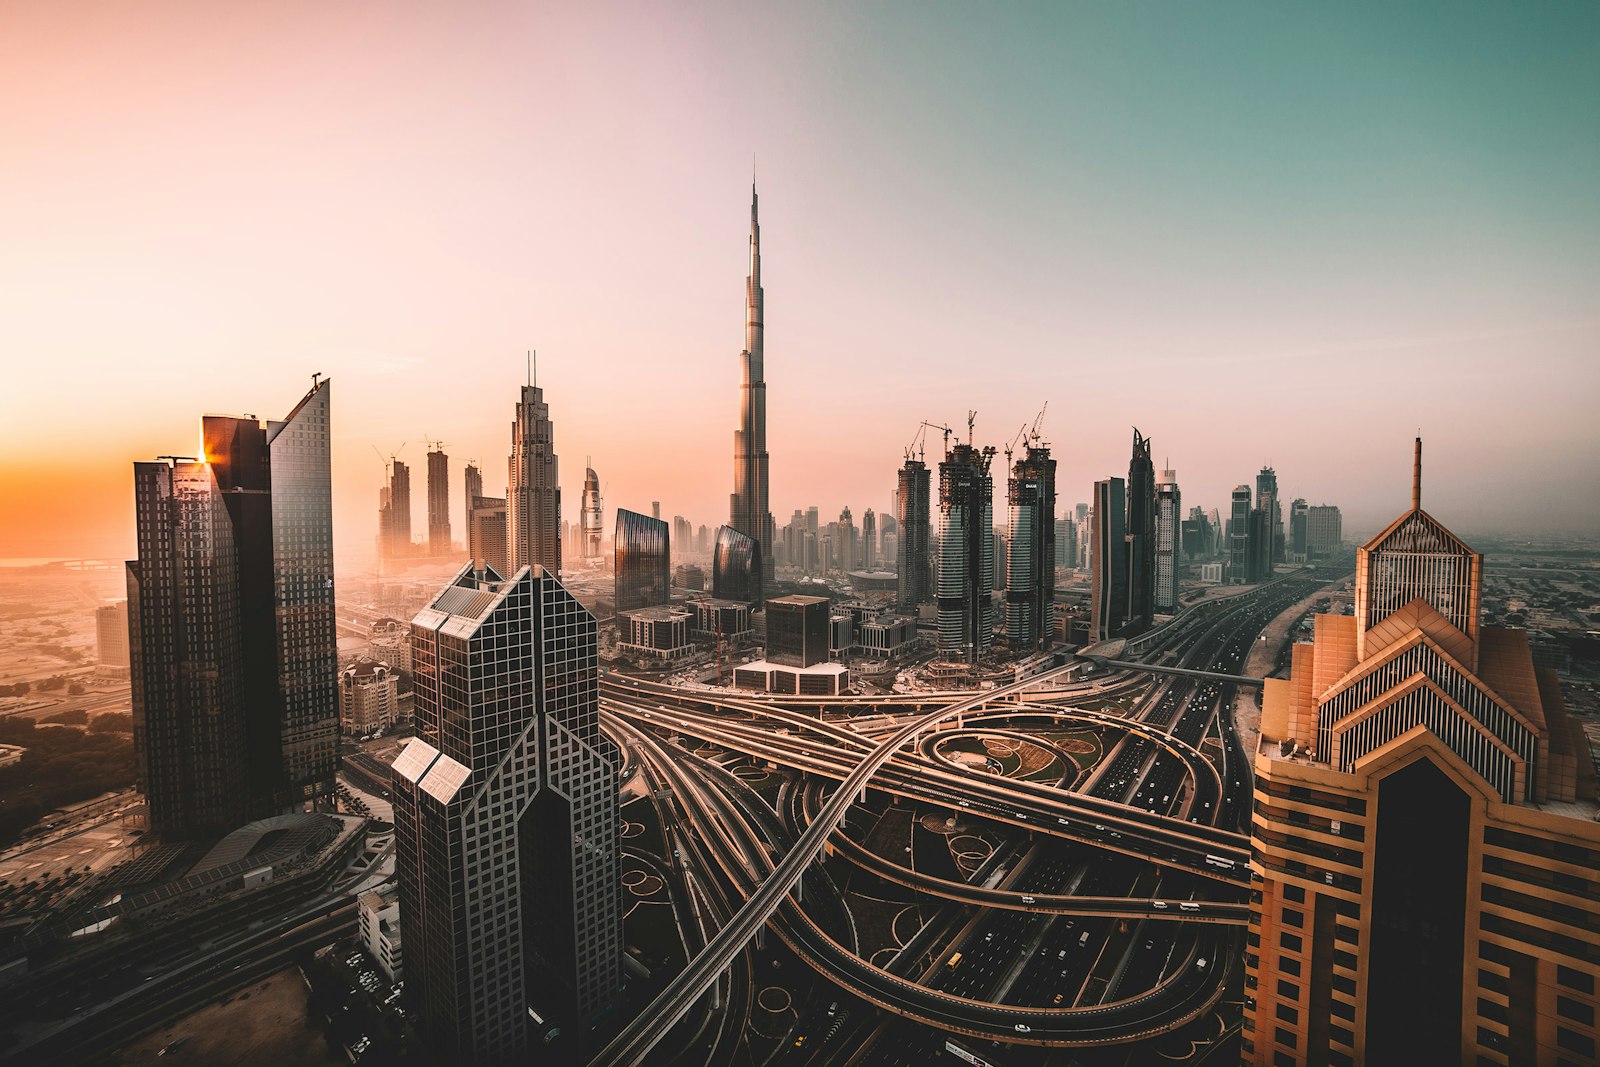
Non-oil activity contributed 79.4% of GDP this quarter, up from 78% a year ago, with non-oil GDP itself growing 4.8% on a real base of AED 485 billion. The label “oil state” no longer describes the economy’s center of gravity.
Trade tells the same story: first-half non-oil foreign trade reached AED 1.937 trillion (+13.1%), and non-oil exports grew 24% to over AED 452 billion. DP World’s ~90 million TEU through UAE ports overtook Hong Kong — quietly challenging the world’s biggest shipping corridors.
Capital has noticed. The UAE drew a record $48.3 billion in FDI (ninth globally) and ranks as the world’s No. 2 greenfield destination with 1,500+ new projects — capturing nearly 40% of Middle East capital in AI, clean energy and climate tech. At home, finance & insurance grew +17%, construction +8.1%, healthcare +7.7%: a services economy in full stride under the D33 agenda.
 05 · SINGAPORE
Smallest country on this list. Biggest trophy: the world’s No. 1 competitive ranking, reclaimed with 5% growth attached.
The Ministry of Trade and Industry raised its 2026 GDP forecast to 4.5–5.5%, with the MAS economist survey’s median at 5.0% — numbers built on the regional AI boom and humming electronics manufacturing. Non-oil domestic exports are surging, and 2026 manufacturing growth is now seen at +8.4%.
Singapore’s chip strategy is precision, not scale: an extra S$800 million budget line for advanced packaging, AI-chip development and 22/28nm process innovation. Applied Materials opened a $500 million Tampines expansion that doubled advanced cleanroom capacity — now in full production for global AI-chip tooling — while UMC’s second-phase fab keeps pulling order flow from chip designers who refuse to put every wafer in one basket.
The harbour itself compounds. Family-office inflows — the region’s hedge against a shifting geopolitical map — pushed bank non-interest income to record highs and the Singapore dollar with it. The MAS has responded by steepening the S$NEER policy band, letting the currency strengthen to cheapen imports and hold core inflation down. In an uncertain world, the safest address just got more expensive — and more crowded.
Tokyo is hiking into strength. Singapore is appreciating into stability. Both are tightening — each in its own currency dialect.
With wholesale inflation at 7.6% and wages compounding, the BOJ is expected to lift its policy rate 25bp to 1.25% on September 17–18, then press toward a 1.75% terminal rate by Q2 2027.
The market’s verdict is already in: the yen at a six-month high, and reassessed carry positions across Asian fixed income.
The MAS keeps a firmly tight stance, steepening the appreciation slope of the S$NEER policy band through H2 2026 — using the currency, not rates, to absorb oil-driven imported inflation.
A structurally stronger Singapore dollar cuts the cost of imports for households while family-office inflows keep the financial sector at record profitability.
September’s deals didn’t happen inside one economy. The real story is between them.
Japan–UAE non-oil trade, +16.7% y/y. Energy buyers became capital partners: AI data centers and climate-tech ventures co-funded by Japanese industrial groups and Gulf sovereign money under the D33 umbrella.
A September supply pact locks in 18 million barrels of additional stable crude for Korea — insulating Asia’s fourth-largest economy from oil-price spikes just as its chip fabs hit peak output.
A refreshed economic memorandum pairs Japan’s precision materials and chip tooling with Singapore’s ASEAN financial-logistics hub — joint incubation for SMEs and hard-tech unicorns, supply-chain de-risking included.
SK Hynix is weighing its first-ever Japanese memory plant in Miyagi — trillions of won across the strait, and the clearest sign yet that chip supply chains are being rebuilt as alliances, not just factories.
Who grows fastest — and on what basis. Read the bars, then read the fine print.
Bases differ: Singapore is the MAS economist-survey median for 2026; UAE is non-oil real GDP growth; Korea is the KDI 2026 upgrade; Japan is revised Q2 2026 annualized growth; Russia is the official H1 2026 estimate. All figures as reported in the September 2026 digest.
A 4.4-point spread between Singapore’s compounding harbour and Russia’s defense-led grind is exactly what reprices currencies, rates and equity risk premia across the corridor.
Notice where the growth is quality-adjusted: Korea’s 3.2% rides a semiconductor supercycle; the UAE’s 4.8% is the non-oil economy alone; Singapore’s 5.0% comes with the world’s No. 1 competitiveness ranking attached.
Japan’s 1.4% is the sleeper — the first print in decades where the domestic household, not the exporter, is the marginal buyer.
“Capital no longer asks which market to enter. It asks which of these five economies compounds while the others argue. This month, the answer is: all of them, for different reasons — and that is the story of the decade.”
One essay. Five economies. Every chart that moved capital across the Asia–Gulf corridor — in your inbox before the markets open.